If insurance denies your biohazard cleanup claim, you receive a written denial letter stating the reason, and you gain the right to appeal with additional documentation. A denial is not the final word. Many denials are reversed when the homeowner supplies the photos, invoices, and policy language the adjuster missed the first time.
Do not accept a denial as a closed door. Treat it as the start of a second round.
The Most Common Reasons Claims Are Denied
Denials usually fall into a handful of categories. Finding yours in this list tells you what evidence will fix it.
The Cause Is Excluded
Some policies exclude specific causes, such as long-term neglect or certain criminal acts. Read the exclusion section itself, not just the adjuster’s summary of it.
Insufficient Documentation
Missing photos, a lump-sum invoice with no breakdown, or no proof of the event can all trigger a denial. This is the most fixable reason, and the most common one I see.
Late Notice
Policies require prompt reporting. A claim filed weeks after cleanup, with no explanation for the delay, invites a denial on timing grounds.
The Work Was Not Covered Work
Some denials argue the cleanup was maintenance rather than sudden damage. Your invoice wording matters here, since it should describe the sudden event and the contamination it caused.
Limits or Deductible Issues
Sometimes the denial is really a math problem. The covered amount after your deductible may be small, or the claim may exceed a sublimit for a category like mold remediation.
Step One: Read the Denial Letter Carefully
The denial letter is your roadmap. It must name the policy provision behind the decision and explain how to appeal.
Highlight the exact exclusion or condition cited. Then pull your full policy and read that section yourself, including its exceptions.
Adjusters sometimes cite a broad exclusion that has a narrow exception covering your situation. I have seen a “neglect” denial reversed because the policy exception covered sudden, accidental events, which is exactly what the cleanup addressed.
Note the appeal deadline in the letter. Deadlines are strict, and missing one can end an otherwise winnable appeal.
Step Two: Gather the Evidence That Changes the Picture
An appeal succeeds on new or clearer evidence, not on stronger feelings. Assemble a file before you write a word.
Photos and Reports
Before and after photos, the cleanup company’s scope of work, and any police or coroner report that confirms the event. Photos taken by the crew carry weight because they are dated and itemized.
The Itemized Invoice
Ask the cleanup company for a line-by-line invoice if you only have a lump sum. Each room, task, and disposal charge should appear separately.
Policy Language in Your Favor
Quote the coverage grant, not just the exclusion. Many policies cover sudden and accidental direct physical loss, and a biohazard event often fits that grant before any exclusion is applied.
A Written Statement
A short, factual statement of what happened, when you discovered it, when you reported it, and what you did next. Keep it to one page and attach the documents it references.
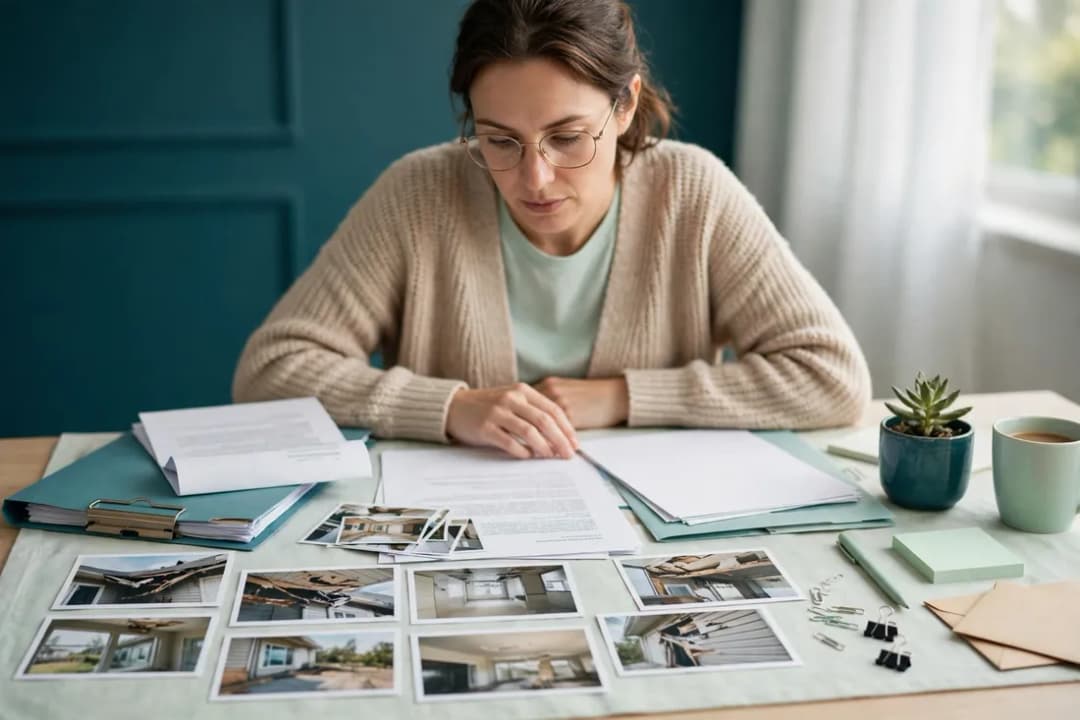
For the original claim steps, review how to file an insurance claim for biohazard cleanup. For coverage basics, see does homeowners insurance cover biohazard cleanup.
Step Three: Write a Clear Appeal Letter
A good appeal letter is short, factual, and organized. It states the claim number, the denial date, and the provision cited, then answers that provision directly.
Structure it in three parts. First, what happened and when. Second, why the cited exclusion does not apply, with policy language quoted. Third, what you are asking for, which is reconsideration and payment of the documented amount.
Attach your evidence file and keep a copy of everything. Send the appeal by a method that proves delivery, such as certified mail or the insurer’s claims portal with a confirmation saved.
If the first appeal fails, ask for a supervisor review. Large insurers have internal escalation paths, and a fresh reviewer sometimes sees what the first one missed.
When to Bring in Outside Help
Some denials need more than a letter. Consider outside help when the amount is large, the insurer stops responding, or the denial relies on a disputed reading of the policy.
A public adjuster can re-document the loss and negotiate directly. An insurance attorney can review whether the denial matches Florida law, particularly the rules on prompt claim handling.
Florida homeowners can also contact the state insurance regulator for guidance. The Florida Department of Financial Services handles consumer complaints about insurers and explains the complaint process.
Do not sign a release or accept a partial settlement while an appeal is pending unless you understand that it may close the claim. A quick partial payment can cost you the rest of the claim.
Preventing the Next Denial Before It Happens
Future claims go smoother when documentation starts on day one. Photograph the scene before cleanup, keep every invoice, and report the event to your insurer promptly, even before you know the final cost.
Ask the cleanup company for a written scope and an itemized invoice as standard practice. Our biohazard cleanup service in Miami documents every job this way, and our trauma cleanup service follows the same standard.
I tell every client the same thing. The claim is won during the cleanup, not after it, because the photos and invoices you collect on the day are the ones the adjuster trusts most.
Summary
An insurance denial is a decision you can challenge. Read the denial letter, identify the exact provision cited, gather photos and an itemized invoice, and appeal in writing before the deadline.
Many denials reverse on better documentation alone. If the appeal fails, escalate to a supervisor, consider a public adjuster or attorney, and contact the state regulator for guidance.
Need help documenting a cleanup for your claim? Contact Hazard Guard or call (888) 976-0045. Our Miami crews are available around the clock, and the call is free.